

The five years before you retire matter more than almost any others. A bad market, a missed deadline or a fuzzy budget hurts most right before you stop working. This pre-retirement checklist covers the five things to get right while you still have time to adjust.
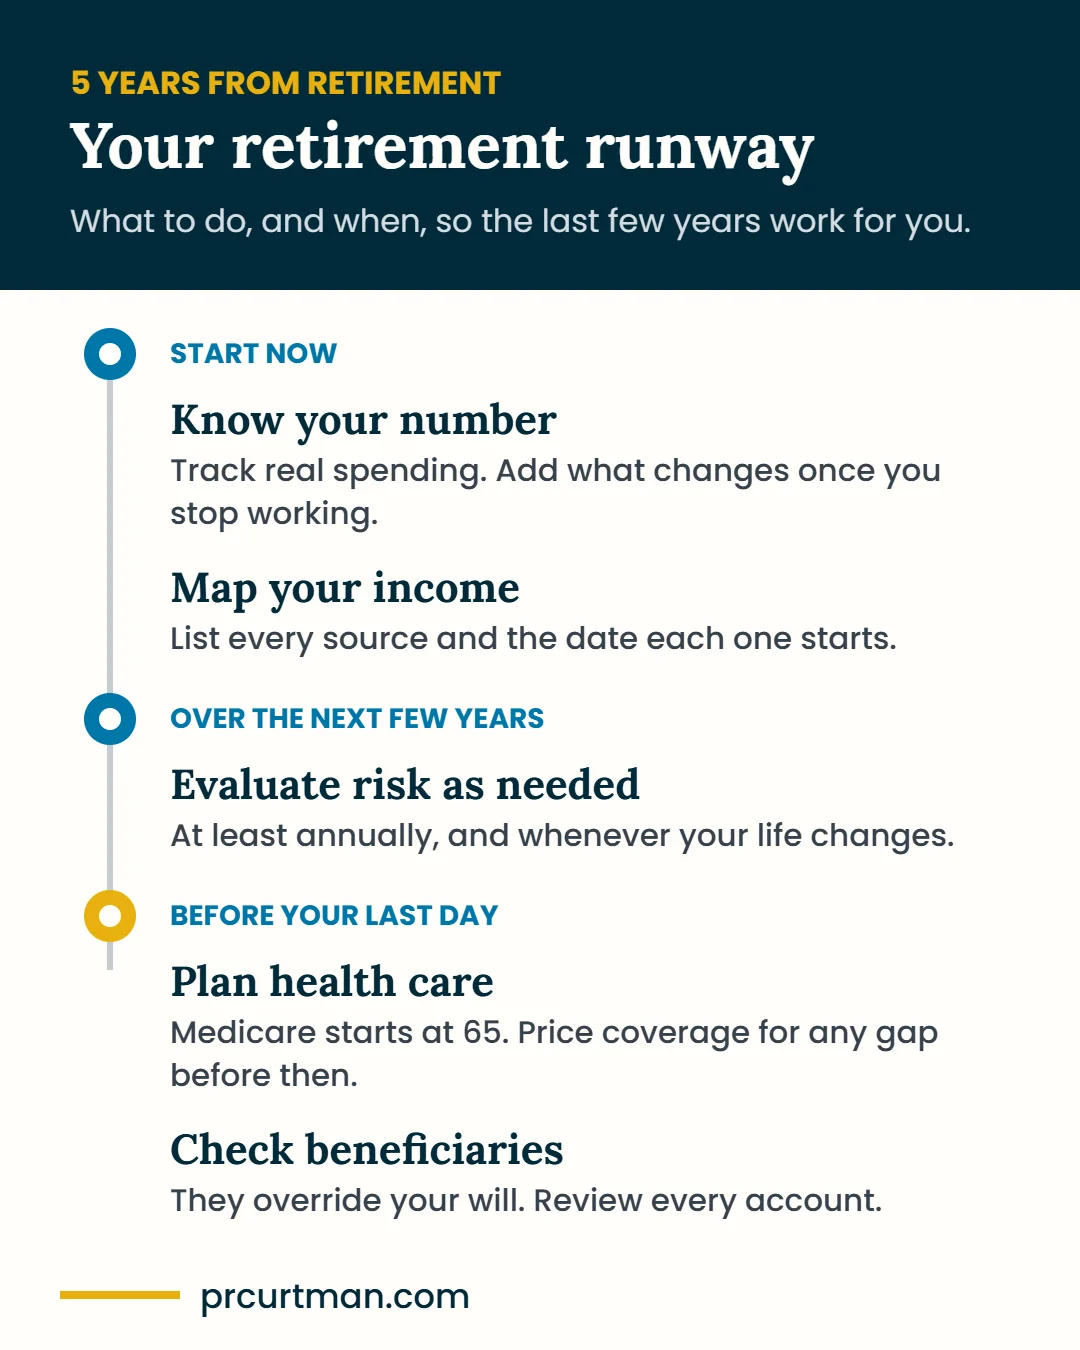
1. Know your number
Start with what you actually spend, not a rule of thumb. Track a few months of real spending, then add what changes in retirement: travel, health care, helping kids or grandkids. Some costs go away too, like commuting and retirement savings.
That monthly number is the foundation for everything else.
2. Map your income
List every source of income you’ll have and when each one starts: Social Security, a pension, part-time work, rental income, and what your savings need to cover. Lay them out on a timeline.
Most people find a gap in the early years, before Social Security or a pension kicks in. Knowing that now lets you plan for it. Two good next reads: When to Claim Social Security and How to Turn Savings Into Retirement Income.
3. Evaluate risk as needed
The mix of investments you own should match how soon you’ll need the money and how much risk you can live with. A big market drop right before or after you retire can do lasting damage, because you’re pulling money out while prices are down.
Review your risk at least once a year, and any time your life changes, like a new retirement date, a health change or an inheritance. Make adjustments on a plan, not in a panic after a rough week.
4. Plan for health care
Medicare starts at 65. If you retire before then, you’ll need coverage to bridge the gap, and it can be one of your biggest costs. Price it out now. If you’ll be on Medicare, learn the enrollment deadlines, because missing them can mean higher premiums for life.
5. Check your beneficiaries
Beneficiary designations on your 401(k), IRAs and life insurance override your will. Make sure every account names the right people, including backups. It takes 30 minutes and can save your family a lot of grief.
Bonus: catch up while you can
Once you’re 50 or older, you’re allowed to put extra money into your 401(k) and IRA each year. If you can afford it, these last few years of saving can make a real difference.
Putting your pre-retirement checklist to work
We help you work through each of these and turn them into one plan, with a portfolio built around the income you’ll need. You work directly with Paul, by appointment, by phone, video, or in person somewhere convenient for you.
Your next step
- Want the full roadmap? Get the free Retirement Income Blueprint.
- Have a quick question first? Ask it anytime in the chat on this page.
- Ready to talk it through? Book a call with Paul.
This article is for education only and isn’t individual investment, tax or legal advice.
