

Tax-efficient investing starts with a simple idea: two portfolios with the same investments can leave you with different amounts after taxes. The difference comes from three habits: putting each investment in the right type of account, choosing funds that don’t create surprise tax bills, and being careful about when you sell.
We don’t prepare taxes or give tax advice. We invest with taxes in mind and work alongside your tax professional.
1. 3 Types of Accounts
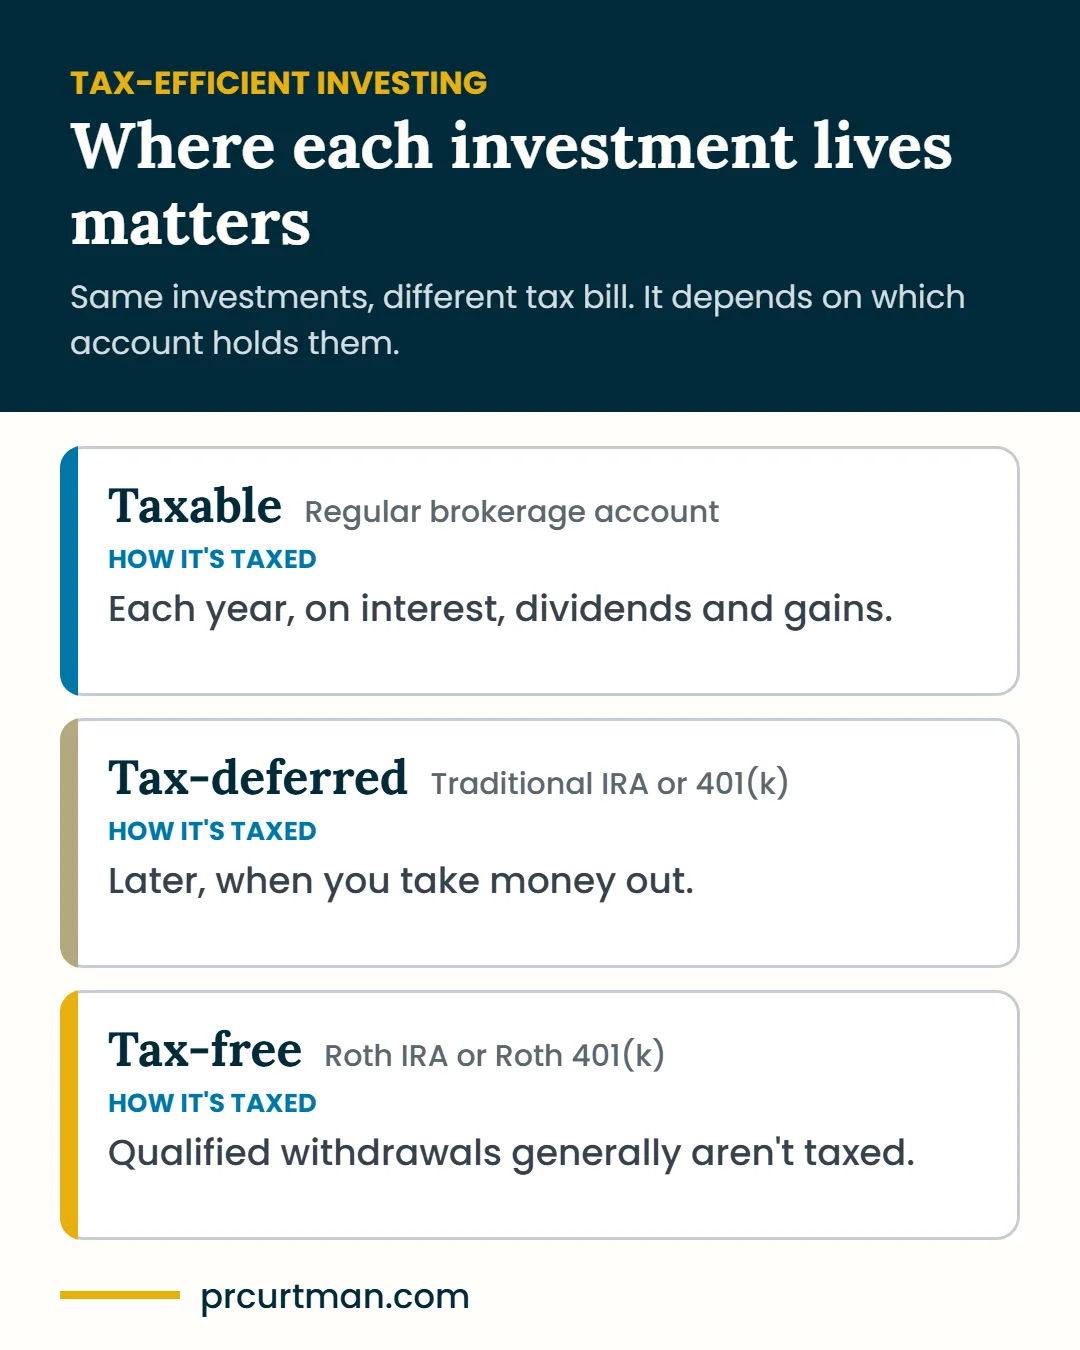
Most people have money in three kinds of accounts:
- Taxable: a regular brokerage account. You may owe tax on interest, dividends and gains each year.
- Tax-deferred: a traditional IRA or 401(k). You generally pay tax when you take money out.
- Tax-free: a Roth IRA or Roth 401(k). Qualified withdrawals generally aren’t taxed.
Where you hold each investment matters. Investments that throw off a lot of taxable income often fit better inside an IRA, while investments you plan to hold for a long time can make sense in a taxable account. This is called asset location, and it’s one of the quietest ways to keep more of what you earn.
2. Tax-efficient funds
Some funds hand out capital gains to shareholders at year-end, even if you never sold a share. In a taxable account, that’s a tax bill you didn’t plan for. Index funds and ETFs often distribute less, though not always. Knowing how these funds distribute interest or gains is important to understanding how they might impact your taxable liability.
3. Careful timing
When you sell matters as much as what you sell.
- Holding period. Investments held more than a year generally get better tax treatment than ones held a year or less.
- Using losses. When an investment is down, selling it can sometimes offset gains elsewhere. There are rules about buying it back too soon, so it has to be done carefully.
- Withdrawals in retirement. The order you draw from your accounts can change how much tax you pay over time. We plan withdrawals with that in mind.
Thinking about moving money from a traditional IRA to a Roth? See Roth Conversions: When They Make Sense.
Where tax-efficient investing fits in
Taxes are one part of a bigger picture: what your money needs to do and when. We build the portfolio around that, keep taxes in view the whole way, and coordinate with your tax professional when it matters. You work directly with Paul, by appointment.
Your next step
- Want the bigger picture? Get the free Retirement Income Blueprint. It covers the order to draw from your accounts.
- Have a quick question first? Ask it anytime in the chat on this page.
- Ready to talk it through? Book a call with Paul.
This article is for education only and isn’t individual investment, tax or legal advice. Talk with your tax professional about your situation.
