

There are three ways to move retirement money into or between IRAs, and they don’t work the same. A direct IRA rollover or a trustee-to-trustee transfer is almost always the cleaner choice, because the money never passes through your hands and nothing is withheld.
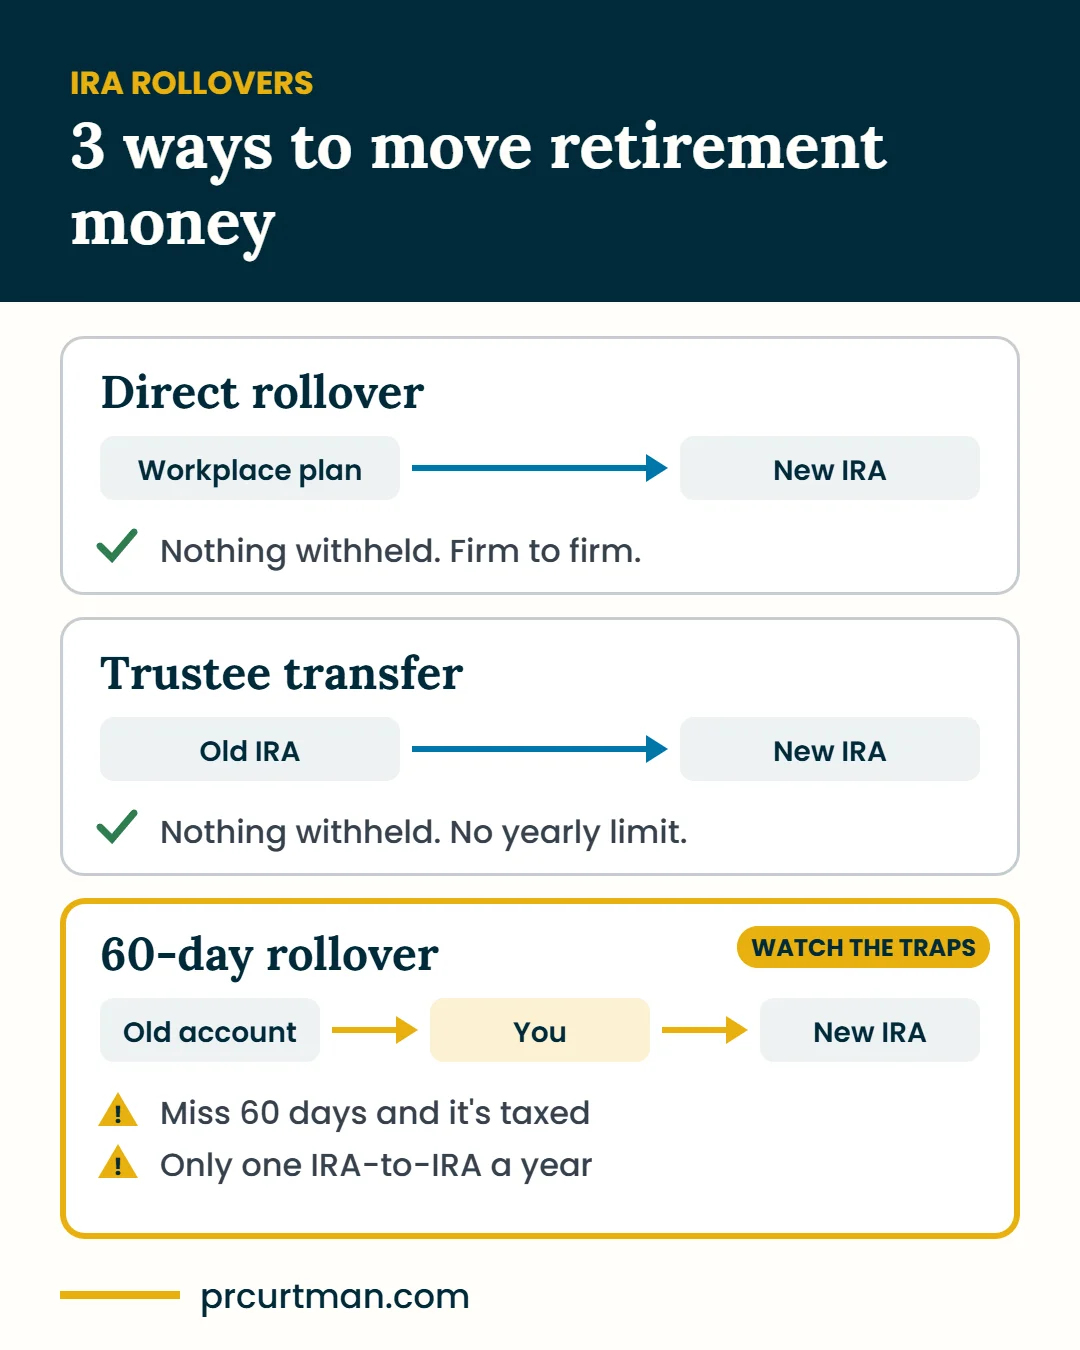
1. Direct IRA rollover: from a workplace plan
Your old 401(k), 403(b) or similar plan sends the money straight to your IRA. You fill out the paperwork, and the check is made out to the new account, not to you.
Nothing is withheld, and nothing counts as a withdrawal. If you’re leaving a job, this is usually the way to move the money. For the full picture on an old workplace plan, see Your Old 401(k): Four Options.
2. Trustee-to-trustee transfer: from one IRA to another
If you already have an IRA and want it somewhere else, the two firms move it directly between themselves. You never touch the money.
There’s no limit on how many of these you can do in a year. It’s the simplest way to combine old IRAs into one place.
3. The 60-day rollover: the one with traps
With a 60-day rollover, the money is paid to you, and you have 60 days to put it into an IRA. Miss the deadline and the money is treated as a withdrawal.
There are two catches:
- From a workplace plan, 20% is withheld. To roll over the full amount, you have to make up that 20% from your own pocket within the 60 days.
- From an IRA, you get one per year. You can do only one IRA-to-IRA 60-day rollover in any 12-month period, across all your IRAs. A second one counts as a withdrawal.
Unless you have a specific reason, skip this method.
Keep like with like
A traditional account goes to a traditional IRA. A Roth 401(k) goes to a Roth IRA. Mixing them up can create a tax bill you didn’t expect, so double-check the account type on every form.
Where we fit in
We handle the paperwork with you and coordinate with both firms so the money moves directly. You work with Paul, not a call center, from the first form to the final statement.
If you choose to have us manage the account, we’re paid our advisory fee for that work. As a fiduciary, we’ll always tell you when leaving money where it is makes more sense. Fee-only, so we do better when you do better.
Your next step
- Want the bigger picture? Get the free Retirement Income Blueprint.
- Have a quick question first? Ask it anytime in the chat on this page.
- Ready to talk it through? Book a call with Paul. We meet by phone, video, or in person somewhere convenient for you.
This article is for education only and isn’t individual investment, tax or legal advice.
